A $2.3 Billion Market Shifts Gears: Inside the Natural Food Colors Market
- Published on October 1, 2026
- CENVIBIO Insights Team
- 7 min read
Natural food colors are no longer a niche choice. According to Grand View Research, the global natural food colors market reached USD 2.3 billion in 2025, and continues to grow under the combined pressure of tightening regulation and clean-label demand. Understanding the structure of this shift — which categories are rising, which applications are brewing below the waterline — beats chasing single hotspots.
Category landscape: incumbents and challengers
Caramel remains the volume king. With the lowest cost per shade and excellent stability, caramel keeps its base in cola-type beverages, bakery and soy-based seasonings — while clean-label versions drive an upgrade cycle of their own.
The carotenoid family expands steadily. Annatto, paprika, lycopene, beta-carotene and lutein cover a broad yellow-to-red spectrum with strong stability in fat-based systems, powering beverages, dairy and savory snacks.
Functionality-led categories outgrow the market. Curcumin, anthocyanins and spirulina blue carry health associations beyond color, and are growing faster than the market in nutrition and premium beverages.
Natural blue completes its zero-to-one. With the phycocyanin system maturing in both regulation and supply (see our earlier deep-dive), blue has turned from "hardest to replace" into one of the fastest-growing shades.
Application waterline: beverages lead, bakery rises
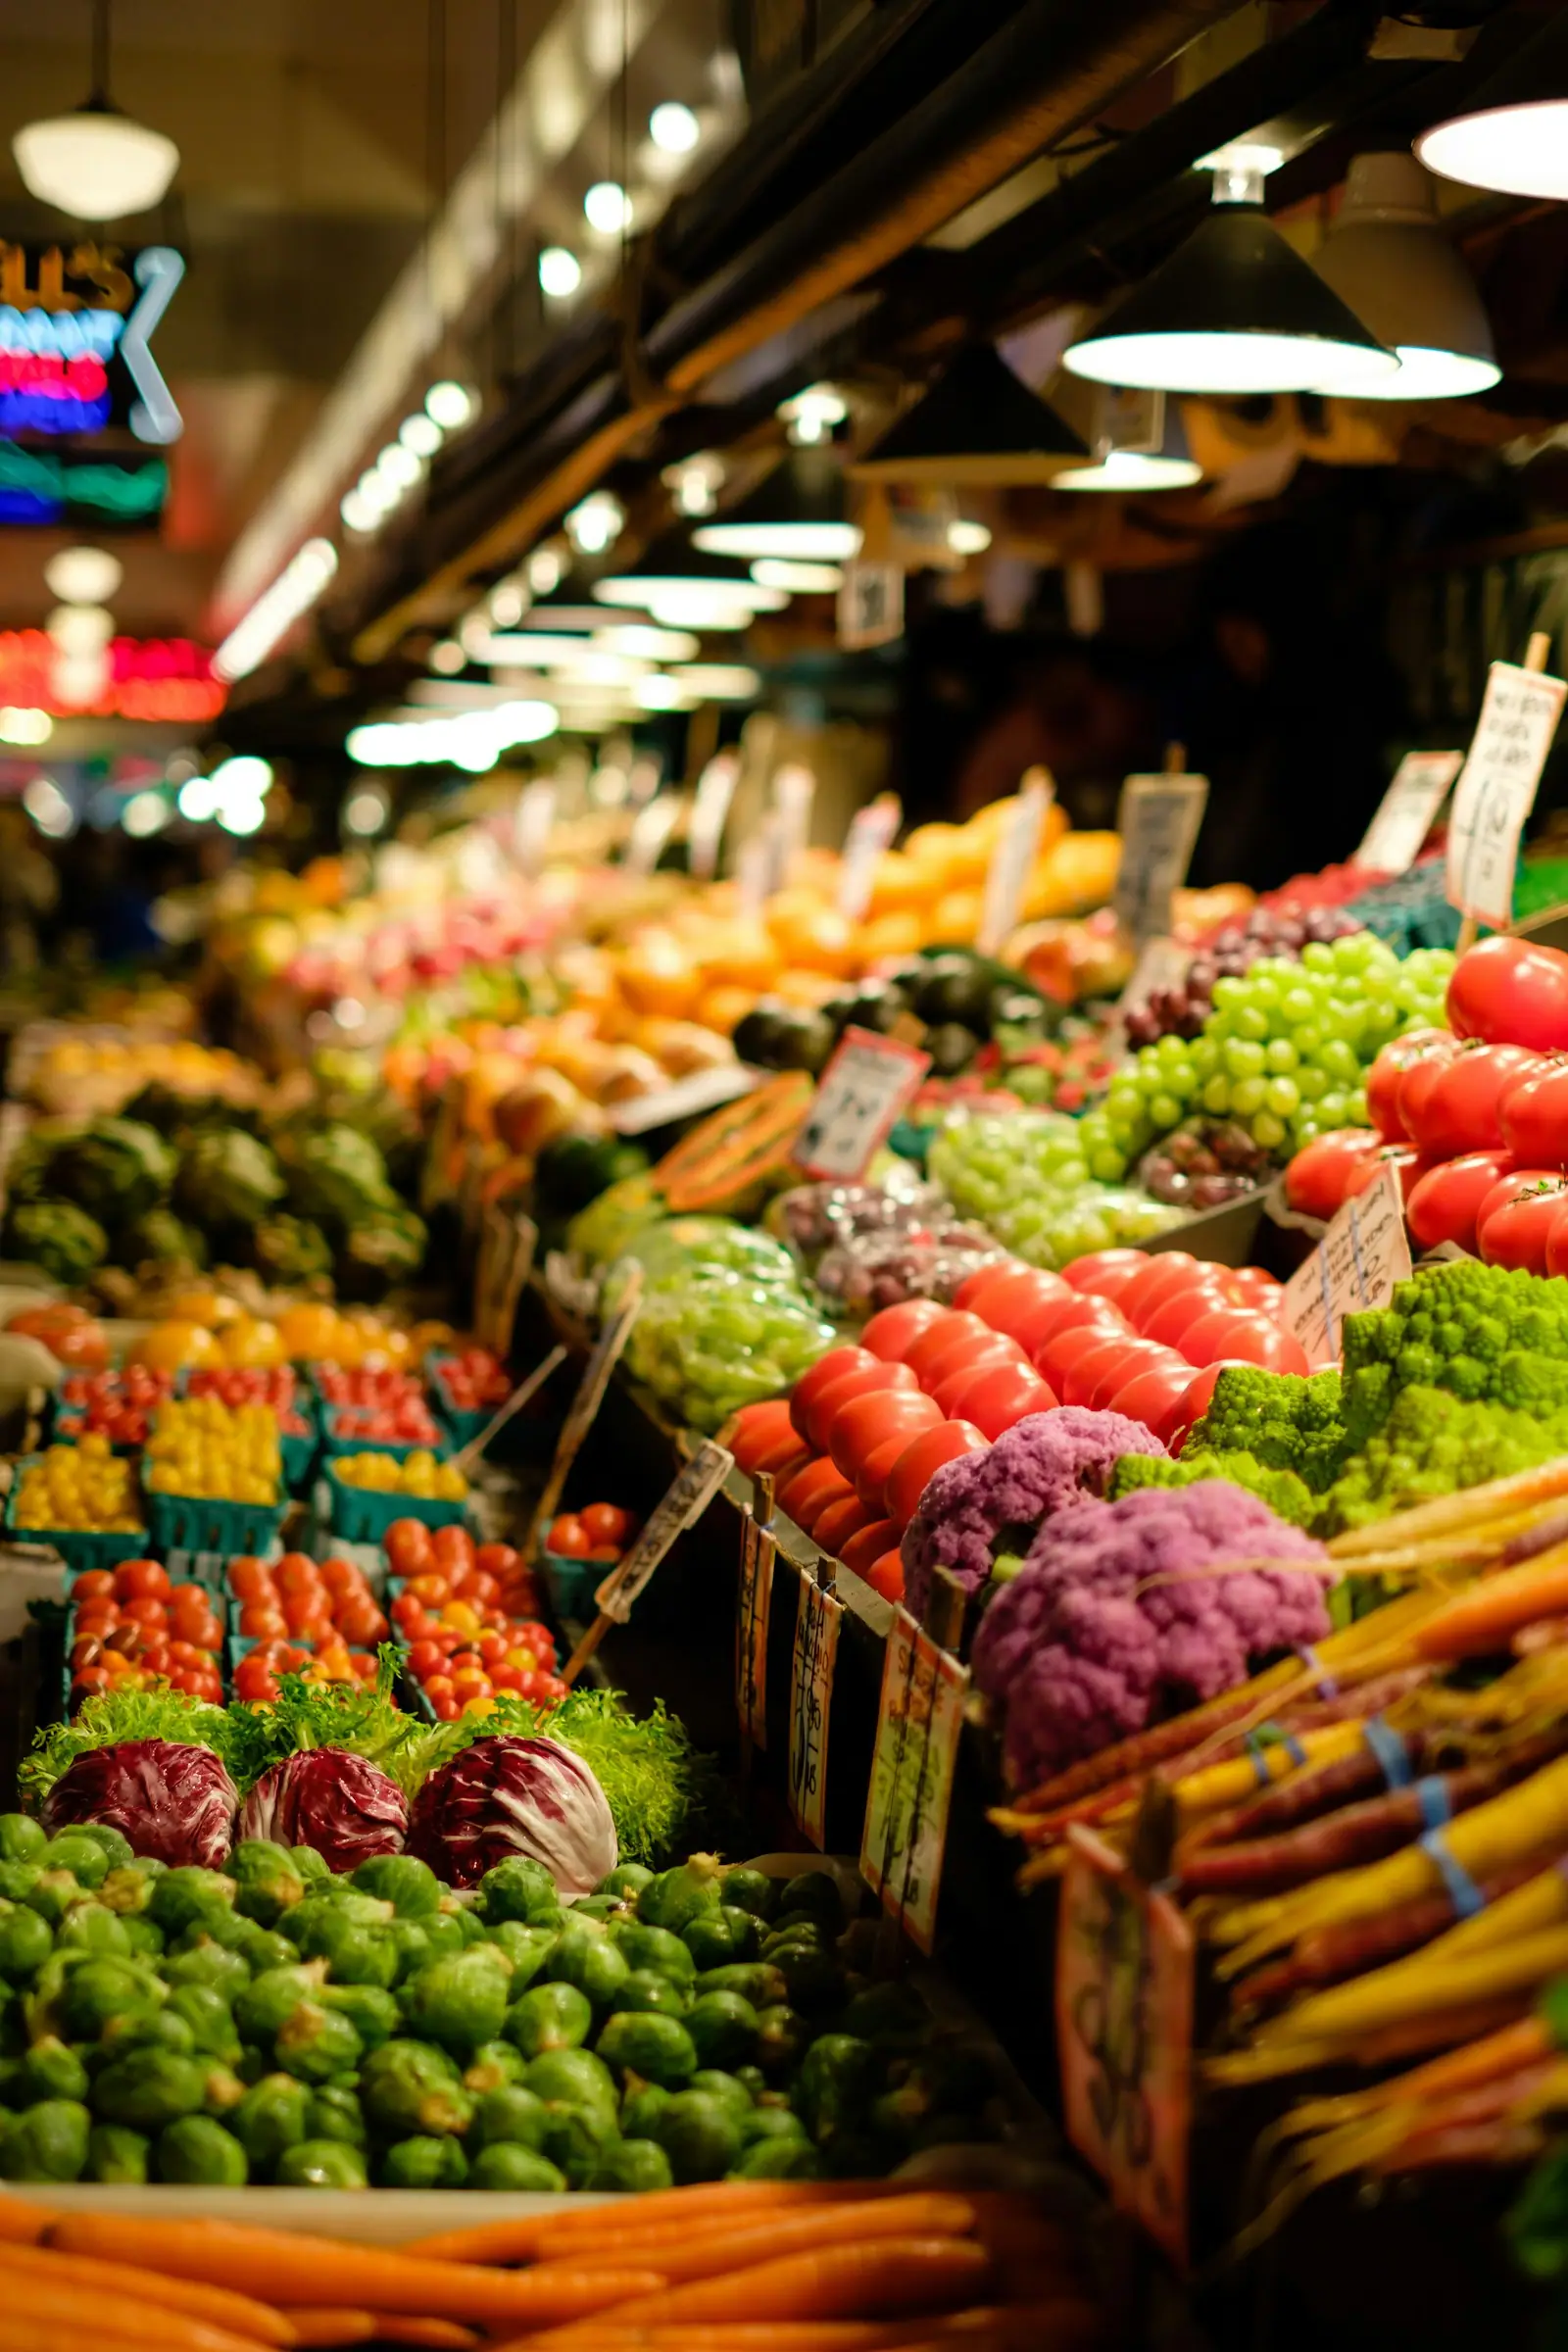
Beverages show the highest natural-color penetration — acidic and chilled systems are friendly to natural pigments and turnover is fast. Dairy and frozen desserts follow; bakery and confectionery are rising as microencapsulation lifts the heat ceiling. Pet food is an often-missed growth pocket: owners' expectations of "human-grade" ingredients are migrating quickly into pet treats.
Regional dynamics: Asia-Pacific's double role
Asia-Pacific is both the largest sourcing origin — the home of turmeric, gardenia, spirulina and other core inputs — and the fastest-growing consumer market. Supply-chain regionalization is underway: procurement teams weighing tariff and geopolitical risk increasingly demand multi-origin backup from suppliers. This matters most for highly concentrated categories such as phycocyanin.
Three calls for the transition period
1. Change the cost lens. Synthetic colors can be a hundred times cheaper per kilogram, but on a coloring-cost-per-ton basis the gap in most categories narrows to an acceptable range. Formulation optimization often hides behind unit-price comparisons.
2. Transition is about cadence. Leading brands run a two-track play: flagships first, long-tail SKUs second — proving out pilot and stability data on hero lines before replicating at scale.
3. Data tools are changing development speed. From color-stability modeling to raw-material traceability, digital tools are shortening natural color development cycles — though application trials and regulatory validation still cannot be skipped.
CENVIBIO's portfolio spans plant extracts, fruit and vegetable powders and water-soluble systems — one-stop color and compliance solutions by category and target market — browse product lines.